The Money Side
Learn how lenders weigh your credit history, cash flow, and the conditions around a loan. Read your own reports, check for errors, and build a record that gives a lender good reason to back you.
Business / Success / Self-help
The Playbook for Becoming Fundable in Business and in Life
By Patrick Duval
Banks decide if they can trust you. So does everyone else in your life.
Pre-order / Notify me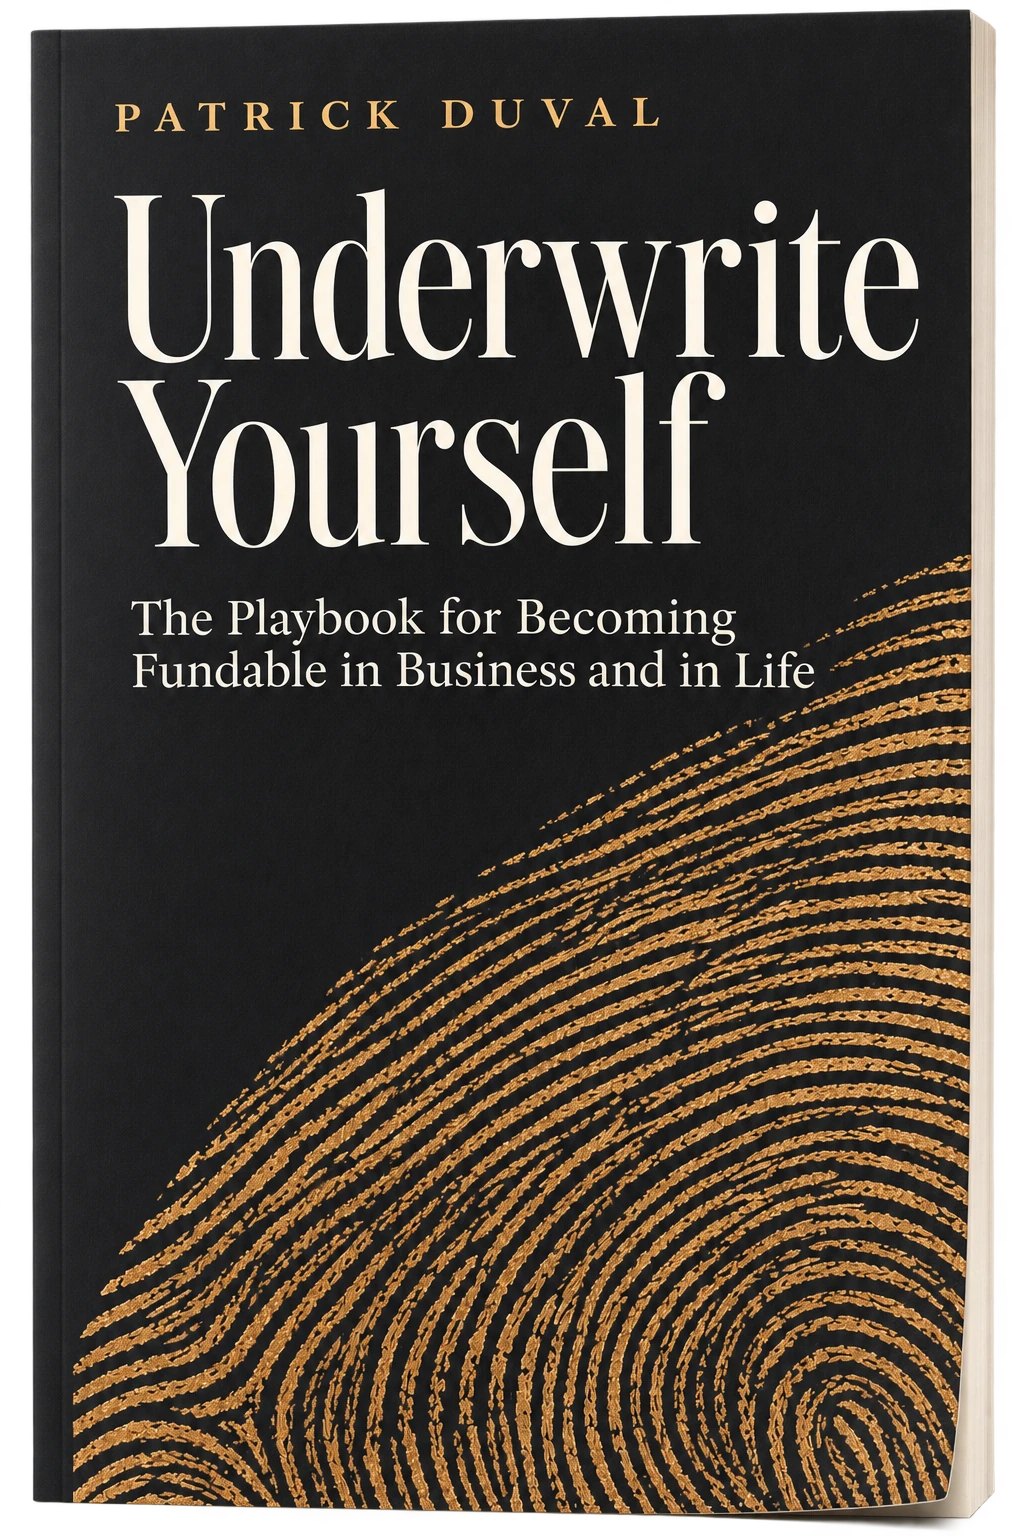
Whether it's a bank or a person, they're all asking the same thing: can I trust you? Patrick Duval was knocked down by the credit system and the legal system. He got back up, and now he teaches others how to become the person everyone wants to back.
This book teaches you how to become someone they say yes to.
Underwriting is how a lender decides whether someone is safe to back.
Learn how lenders weigh your credit history, cash flow, and the conditions around a loan. Read your own reports, check for errors, and build a record that gives a lender good reason to back you.
Family, friends, partners, and colleagues pay attention to what you do. Keeping a promise, admitting a mistake, and showing up again give people a record they can believe in.
People remember what happened the last time they counted on you. Give them a reason to count on you again.
Ask what led to the decision. Once you know the reason, you can decide what to do next.
Correct what is inaccurate. Then start adding a history of commitments kept.
One payment or one promise is a start. Repetition gives that act a history.
Read the terms, check the reporting dates, and understand your rights before choosing your next move.
Use what you have learned to make an introduction, explain a rule, or give someone their first opportunity.
Working outlines, subject to change.
Rebuilding your credit history and your life story. Start with what’s on the record. Check the details on your credit reports. Think about the promises people remember you keeping, and the first promise you could keep to begin earning someone’s trust again.
What you own and what you stand on. A lender may ask what assets can secure a loan. In life, a different question matters. Which values, beliefs, and relationships do you stand by when sticking with them costs you something?
Your cash flow, energy, patience, and discipline. Work out what is left after the bills are paid. Then look at an ordinary week. Before promising anyone more, ask what you have the money, time, and energy to deliver.
What no spreadsheet captures but everyone judges. Consider the call you make when you know you will miss a deadline. How early you speak up, what you take responsibility for, and what you do next tell people a great deal about you.
Reading the moment and knowing the rules. A sound plan can run into a tight market or a change in lending criteria. Find out which rules apply, what has changed, and whether a different time or set of terms would give your plan a fair hearing.
What to do when the answer is no. Ask what drove the decision. An error on a report, insufficient income, and poor timing call for different responses. A refusal gives you a place to start asking better questions.
Practical steps to qualify for capital and opportunity. Put the request in plain language. Explain what you need, how you will use it, and what evidence supports your plan. Give the person across the table enough information to make their own decision.
Success is real when you back someone else. Think of the person who first gave you a chance. Backing someone else might mean an introduction, a first order, or an hour spent explaining a process they have never seen before.
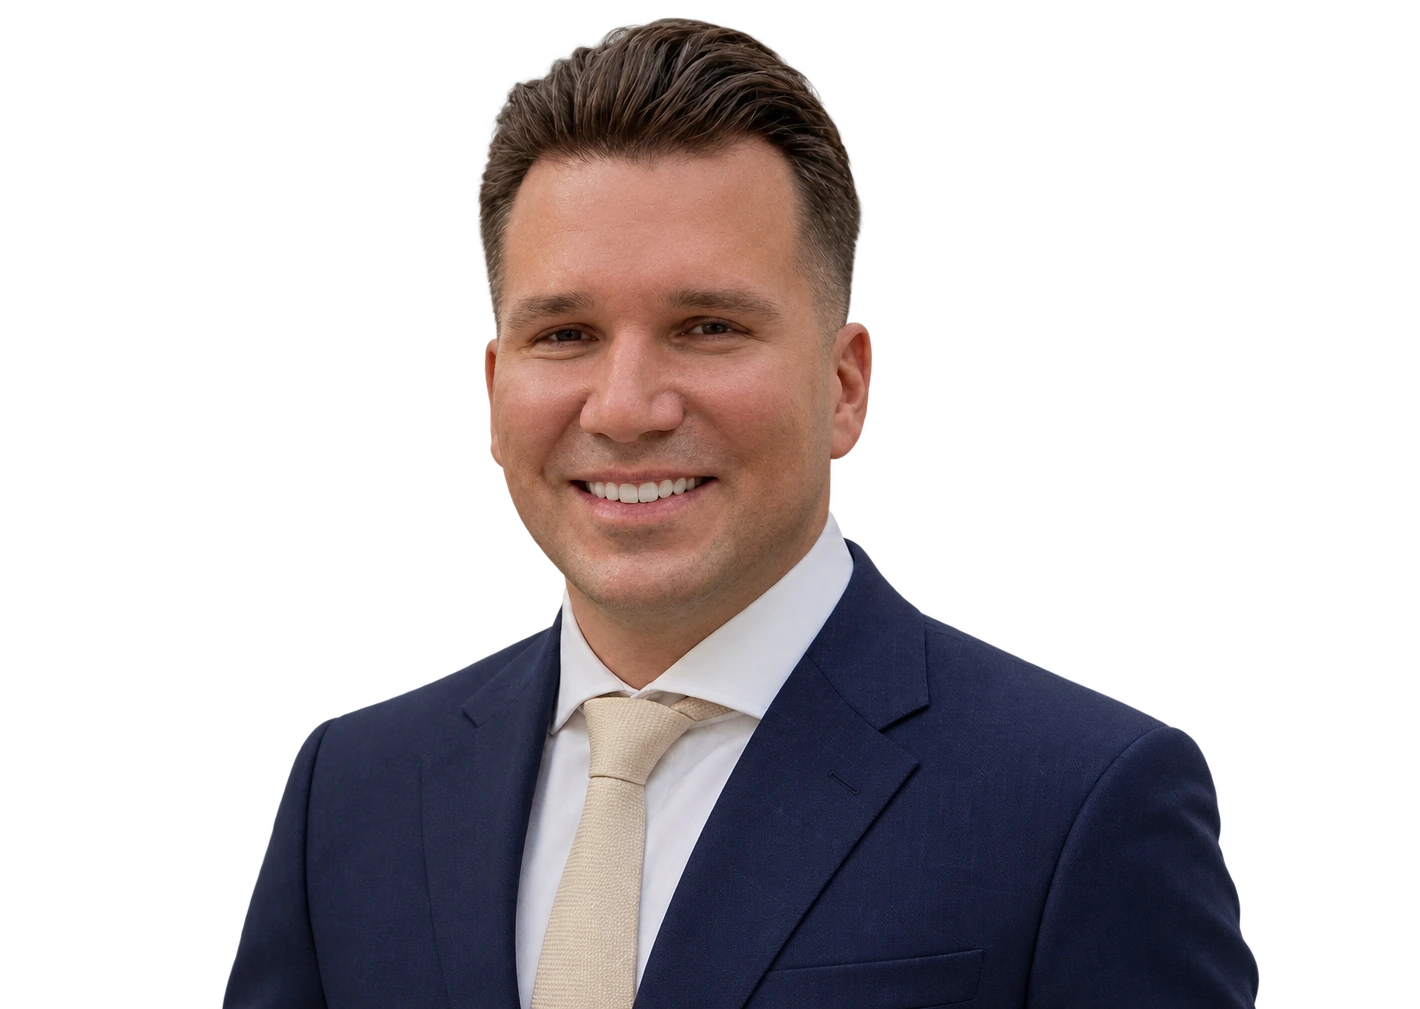
About the author
Patrick is a Houston-born entrepreneur, real estate broker, and co-founder of Remove Credit. His own struggles with credit reporting and the legal system led him to study consumer law. Today he helps people understand their credit files and prepare for financing.
Read Patrick’s biographyRelease date
To be announced.
Email signup
Release notifications will be available here when signup opens.
Where to buy
Pre-order and retailer links will appear here when available.
Endorsements and reader testimonials
Forthcoming.